Yesterday’s jobs report from Challenger, Gray moved markets: layoff plans for January were up 118% from last year and the highest for any January since 2009, during the GFC. ADP’s employment gains for January were less than half of market forecasts, and December’s job openings numbers (BLS) dropped to their lowest level since 2020. Challenger data can be volatile, so next week’s release of the jobs, jobs, jobs report will be closely watched (delayed due to this week’s short shutdown). The concern is that the “no hire, no fire” flat jobs market may be eroding. Fed Futures still predict two “pause” meetings (March/April), with a 70% chance of a cut in June (the first meeting with incoming Chair Warsh). Note that futures chances of an earlier cut have risen slightly on the employment news.
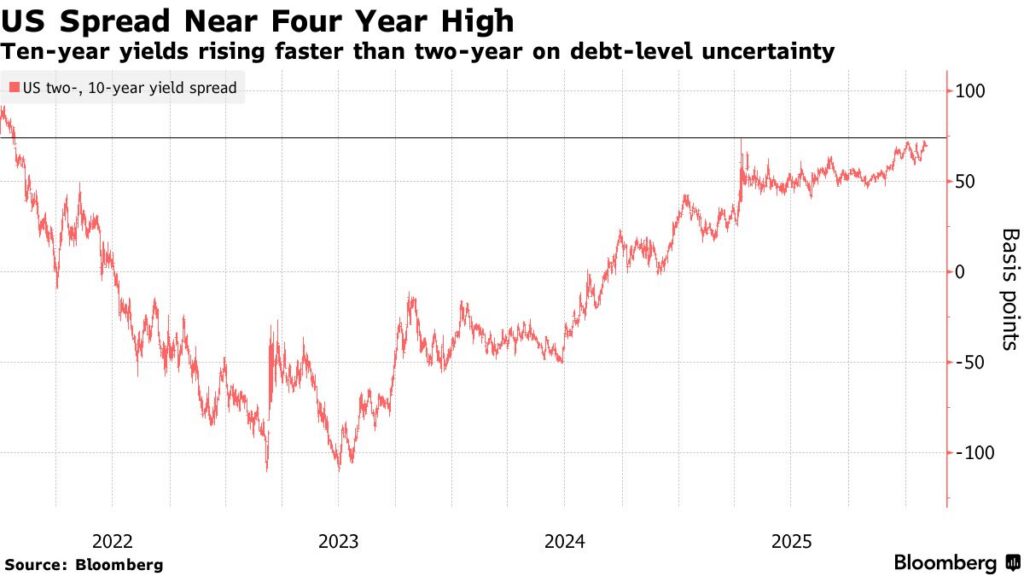
The 10-year Treasury sits at 4.22% after hitting a low of 4.16% yesterday following the Challenger report. Speaking of the 10-year Treasury, this week’s Treasury Bond Sales Announcement confirmed speculation of a change in strategy: upcoming auctions will be skewed more towards short-term Treasury Bills (1 – 12 month terms), as the Treasury is trying to avoid overloading 10, 20 and 30-year Notes and Bond issuance, while buyers are increasingly demanding term premium. The yield curve steepened on the news (chart below), as the closely watched “2-year to 10-year” spread is the highest in four years…(more on this next week). Stay tuned…