Today’s jobs report is the first “on-schedule,” complete release since September (due to the shutdown). The data was mixed, as the economy added just 50,000 jobs (vs. 75,000 expected) in December. This closed the book on 2025 as the worst year for job creation since 2009 (except for the 2020 Covid disruption). Just 584,000 jobs were created in 2025, compared to 4 million in 2022 and 2 million in both 2023 and 2024. Slowdown factors include AI disruption, mid-year tariff concerns, and government layoffs. Overall, employers are not engaging in mass layoffs. The unemployment rate fell to 4.4% (vs. 4.5% expected); however, the decline was partially due to technical revisions, leaving the employment picture still “muddy.”
The 10-year Treasury is at 4.17%, after briefly breaching the key technical level of 4.20% before immediately dropping. What about the Fed? Today’s data dropped futures market odds for a January rate cut from about 15% to 5%. The futures market now indicates no rate cut until June, with three consecutive “pause” meetings. Fedspeak: Fed Gov Kashkari stated, “My guess is we’re pretty close to neutral right now…We just need to get more data to see which is the bigger force. Is it inflation or is it the labor market?” Being in the neutral-rate range would indicate that the bar for future cuts could be rising among a more “centrist” group of policymakers.
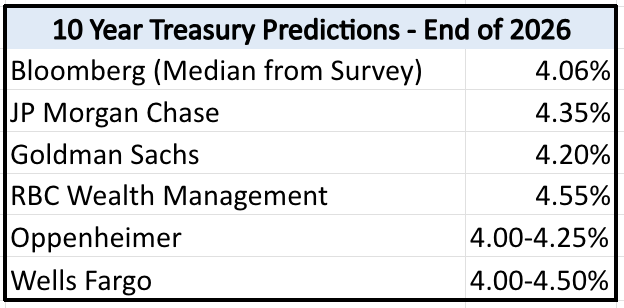
Reading the various comments from the investment banks, most analysts expect further interest rate cuts by the Fed. However, persistent inflation and continued high government debt issuance are expected to keep long-term yields from falling dramatically (“term premium”). Stay tuned…