Transaction Overview
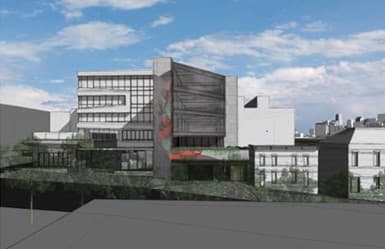
George Smith Partners placed the $11,000,000 take-out of a single-tenant office build-to-suit leased for 10 years to an investment grade GSA tenant located in a secondary Southern California market. The tenant, a Children’s and Family Services office had required security upgrades in the building design and construction. Sized to a 1.25 DCR, loan proceeds netted 80% of the total development cost allowing for a partial recapitalization of Sponsor equity beyond the construction loan. The loan was funded less than two weeks post certificate of occupancy issuance but prior to the tenant opening for operations. Fixed for five years at 5.0%, the loan will reset for the second five year term at the CMT+2.25%. There is no pre-payment penalty.
Challenges: This capital provider traditionally seeks a personal repayment guarantee from at least 51% of the ownership stack. While the 20% GP would sign, none of the limited partners were available to guarantee. Interest rates moved up post application and the Sponsor sought to close as quickly as possible to preserve his applied for coupon. Although the tenant accepted the space and initiated rental payments, they opted to delay their opening date due to the pending holidays. Our permanent loan lender thus questioned if the property was in fact stabilized without an operating tenant. Security cost improvements were amortized into the ten-year lease.
Solutions: A waiver was requested and granted that accepted a personal guarantee from the manager who holds 20% of the Borrower. Support from the investment grade tenant furthered the argument for this waiver. To mitigate stability concerns, the construction loan and loan finance costs were paid at funding. The return of equity will be distributed once the tenant is “doors open” and commences operations. Our underwriter reviewed the requirement for the security needs and understood the benefit of the guaranteed cash flow from the credit tenant. The capital adviser agreed to raise their LTV constraint from the applied for 67% LTV to 75% LTV. There was no reduction in loan proceeds.